


Leverage the Delaware Statutory Trust alternative in a § 1031 like-kind exchange
Vol. 82, No. 2 / March-April 2026
 Benjamin Newhouse is the founder of Vineyard Asset Management, LLC, a boutique wealth management firm. Through years of experience and his current affiliations, Newhouse focuses on applying the use and benefits of various DSTs and private placement investments for clients. He graduated from the University of Tulsa College of Law in 2000. In addition to holding numerous financial securities licenses, Newhouse is also a member of The Missouri Bar and a certified public accountant licensed with the Missouri State Board of Accountancy. He holds the personal financial specialist credential available to CPAs who acquire additional specialized training within various financial management bodies of knowledge. He teaches business law as an adjunct professor at Mission University in Springfield. He can be contacted at b.newhouse@diversify.com.
Internal Revenue Code § 1031 offers one of the most powerful strategies available to business owners and real estate investors to continue deferring potential capital gains liabilities that would otherwise become due upon the sale of an appreciated asset.1
While many lawyers who specialize in tax or real estate law are familiar with the requirements involved in conducting a § 1031 exchange, it generally appears that very few such specialized lawyers and certified public accountants are aware of how Delaware Statutory Trusts can be effectively leveraged to facilitate a fully qualified tax-deferred exchange transaction under § 1031.
Typically, clients engaging in a § 1031 exchange transaction simply elect to “swap” one directly owned investment property for another. However, just as the real estate market has evolved, the Internal Revenue Service, via private letter ruling,2 has also evolved by recognizing and blessing the use of properly structured DSTs to also qualify to receive § 1031 taxdeferred exchange treatment.
 While § 1031 exchanges and DSTs are most frequently discussed in the context of tax and real estate practice, their implications extend well beyond those specialties. In contemporary legal practice, lawyers across a wide range of disciplines increasingly encounter transactions, planning matters, and disputes that implicate § 1031 deferral rules and DST investment structures.
Business and corporate lawyers advising closely held companies, professional practices, and family-owned enterprises often confront situations in which the operating business and the underlying real estate are economically distinct assets. DSTs offer a mechanism for reinvestment that permits continued tax deferral without requiring ongoing operational control, an outcome frequently aligned with succession or exit planning objectives.
Estate planning and trust lawyers likewise encounter DST-related issues when advising clients whose wealth is concentrated in illiquid real property. The ability to fractionalize ownership interests through DSTs can facilitate equitable distribution among beneficiaries, mitigate forced sales, and preserve eligibility for a step-up in basis at death.
Family law practitioners may also confront DST considerations in the division or disposition of income-producing property incident to divorce. Because the tax consequences of real estate liquidation can significantly affect the net marital estate, awareness of § 1031-compatible structures may influence settlement strategy and valuation analyses.
Finally, litigators and general practitioners increasingly encounter DSTs in disputes involving fiduciary duties, securities law disclosures, suitability determinations, and professional negligence claims. A working understanding of DST mechanics and limitations enhances issuespotting and enables more effective collaboration with tax and financial professionals, thereby advancing competent client representation.
This article explores the basics of § 1031 exchanges, the structure and advantages of DSTs, important legal considerations, and best practices for advising clients when considering use of this modernized vehicle to conduct an exchange transaction.
Legal framework of § 1031 exchanges
Like-kind property
Real property held for investment or business use can be exchanged for like-kind property.3 When properly exchanged, the transaction is essentially a swap for new property, which will not trigger a taxable event when a capital gain might ordinarily have otherwise become recognized. However, § 1031 merely defers recognition of potential taxes due; it does not forgive them.
Exchanges using § 1031 must adhere to very strict rules and time horizons. One of the first obstacles to satisfy is to ensure the new investment (or business-use property) meets the IRS’ definition of like-kind property.4 Section 1031 does not fully define this “likekind” term, but it does specifically prohibit the definition from being attached to non-real property such as corporate equities, bonds, real estate investment trusts, etc.5 Like-kind real property is defined for § 1031 purposes to be of the same nature or character to the property being exchanged. It is not a reference to its quality or grade.6 The property must also be located within the United States.7
For example, if Taxpayer A owns a commercial warehouse building and receives rental income from its tenants, the real estate is clearly being held as an investment asset. However, if Taxpayer A were to then exchange it for a parcel of subdivided vacant land marketed for immediate resale as residential or commercial lots, then the IRS may treat the transaction as a taxable sale rather than a like-kind exchange.8 Even though both the relinquished and exchanged assets are real property as required by § 1031, since the vacant land is held primarily for sale, it may not meet the definition of like-kind property because the latter asset is not held for investment or business use.9
Conversely, if Taxpayer B owns an apartment building from which she also collects rental income and then uses § 1031 to exchange it for multiple acres of raw, unimproved land with the intent to hold it for long-term appreciation and eventual resale, the exchange should be deemed like-kind because she is exchanging one real estate investment property for another, despite the significant differences between the quality or grade of the real estate.
Time limits
Exchanges under § 1031 must also meet strict time limits. The IRS will never extend additional time for any reason to a party seeking § 1031 tax-deferral benefits if these prescribed limits are exceeded. There is a hard cap on the time the IRS allows a taxpayer to perform the various steps necessary to complete a qualifying § 1031 exchange transaction.
In this regard, the first time hurdle is the 45-Day Rule.10 The exchanging party must formally and specifically “identify” the potential replacement property (or properties) to be acquired within 45 days of the closing date for the sale of the relinquished property.11 Using the example above, Taxpayer B who sold her apartment building would need to declare and identify that she was going to use the proceeds from her sale to purchase the specifically described vacant land within this time window.
To satisfy § 1031’s identification requirement, the exchanging party must satisfy one of the following three rules:
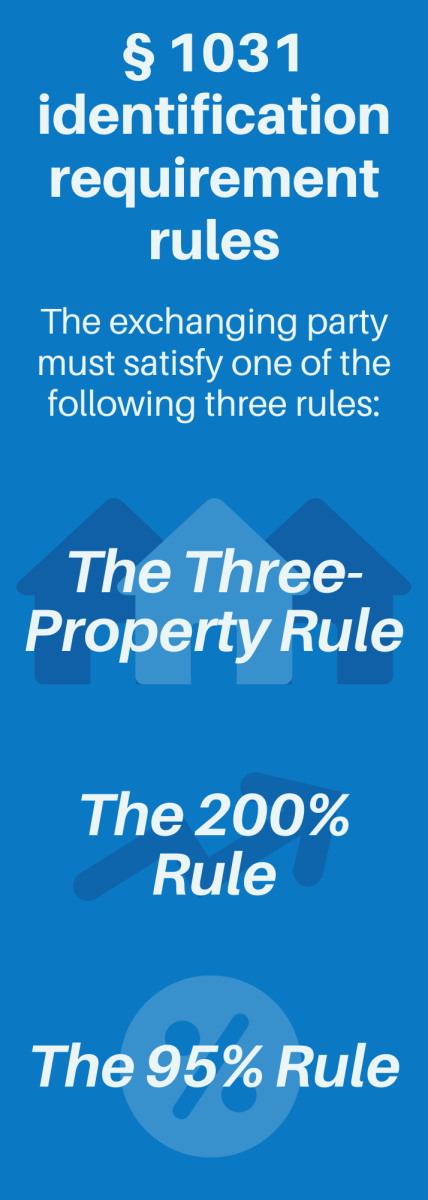 1. The Three-Property Rule allows the exchanging party to identify a maximum of three potential replacement properties to be used, regardless of their aggregate fair market value.12
Here, Taxpayer B sells her apartment building for $13 million. Within 45 days, she can identify, for example:
- vacant land valued at $9 million,
- an industrial warehouse building valued at $8 million, and
- a rental house valued at $450,000.
She can then acquire any, all, or a combination of these properties, provided the aggregate or combined values at least meet or exceed the $13 million sales price of her apartment building.
2. The 200% Rule only denies the exchanging party satisfaction of replacement property identification if the aggregate fair market value exceeds 200% of the relinquished property’s sale price.13
When Taxpayer B sells her apartment building for $13 million, she can identify any number of properties up to $26 million ($13 million multiplied by 200%) in replacement property value. Thus, Taxpayer B can identify additional properties for potential or back-up use beyond just the three properties illustrated in the previous rule, as their aggregate value was only $17.45 million, still short of the $26 million value permitted under this exception.
3. The 95% Rule: If the exchanging party violates the two previous rules, the replacement property identification can still be deemed satisfactory, but only if the taxpayer actually, and timely, acquires 95% or more of the total fair market value of all identified properties.14
If Taxpayer B identifies 10 like-kind real properties with an aggregate fair market value of $32 million (thus violating both the three-property and 200% rules), she can still satisfy the identification requirement if she actually acquires at least $30.4 million worth (95% of $32 million) of all the formally identified assets. If she fails to obtain that high threshold, then her entire attempted exchange becomes taxable.
The second non-negotiable time hurdle is the 180-Day Rule.15 Under this time requirement, the exchanging party must acquire the replacement property or properties within 180 days of closing on the sale of the relinquished property or the due date of the exchanging party’s tax return, including extensions, for the year of transfer of the relinquished property, whichever occurs first.16
So, even if Taxpayer B properly and timely identified the replacement property within the 45 days allotted, she still must close on the identified property before the 180 days expire. Abandoned or delayed closings are not an unusual occurrence. If the purchase/sale negotiations go sideways after the 45-day identification period expires and Taxpayer B does not have a sufficient remaining amount of aggregate fair market value identified, she cannot possibly proceed to complete the exchange under § 1031 as there are no extensions of time.
Thus, parties seeking to conduct a § 1031 exchange are always at risk for noncompliance when the replacement property identified is a traditional real property asset. However, identifying a DST for potential use during the initial 45-day time requirement can significantly reduce this risk.
Reinvestment and debt replacement
If both the like-kind and time elements are satisfied, the exchanging party must still meet three further requirements to receive the full § 1031 tax deferral.
1. Reinvest all net exchange proceeds from the sale of the relinquished property.17
If Taxpayer B keeps any cash proceeds from the sale, that amount is treated as “boot” and is a recognized capital gain.18
2. Replace the debt of the relinquished property with equal or greater debt.19
Assume Taxpayer B’s relinquished property (the apartment building) had $600,000 in debt. If the replacement property had only $425,000 in debt, she would need to contribute $175,000 ($600,000 minus $425,000) in new cash to avoid incurring taxable boot.20
However, if she obtained net cash proceeds (equity) of $12.4 million (the $13 million sales price minus the $600,000 property debt), and then decided to withhold $400,000 in cash and only invest $12 million and then takes on additional $575,000 in debt for the replacement property (the $13 million purchase price minus the $425,000 embedded debt of replacement property equals the $12.575 million taxpayer’s required equity contribution), she would raise her replacement property embedded debt from $425,000 to $1 million via the additional $575,000 debt.
By withholding the $400,000 equity and replacing it with financing, Taxpayer B would receive taxable boot of $400,000. Thus, equity may replace debt, but debt cannot replace equity without suffering a taxable event.21
3. The purchase price of the replacement property must be equal to or greater than the sales price of the relinquished property. Note: Closing costs are prohibited from being part of this equation.22
Assume Taxpayer B sells her apartment building for $13 million. The new replacement property or properties must at least aggregately cost $13 million. If she were to purchase a set of properties for $12 million, she would realize a taxable gain of $1 million ($13 million minus $12 million) unless she reinvested this amount via additional cash or qualifying improvements for the replacement properties.23
Use of a qualified intermediary
Though not explicit within § 1031, the exchanging party cannot take actual or constructive receipt of the exchange proceeds upon closing on the sale of the property being relinquished; doing so would violate IRC § 1001 and thus immediately disqualify the exchange from obtaining tax deferral.24
To avoid this fate, the exchanging party uses a qualified intermediary to take actual or constructive receipt of the exchange proceeds on their behalf.25 Thus, it’s important to enlist and coordinate the services of a QI before proceeding to close on the sale of the relinquished property.
 Entity consistency requirement
Finally, for the § 1031 exchange to be successful, both the relinquished and replacement properties must be held by the same taxpayer/entity.26 Other than this requirement, any tax-paying entity — corporations, partnerships,27 individuals, limited liability companies, trusts, etc. — is entitled to the benefits of § 1031.28 Even non-U.S. citizens who own property in the U.S. can use § 1031.29
Summary for § 1031: five pitfalls to avoid
The exchanging party needs to avoid the following to receive the full tax deferral benefits available under § 1031:
1. Control of proceeds. Solution: Use a QI to take actual or constructive receipt of sales proceeds.
2. Failure to trade up or trade even. Solution: Apply all cash/ equity received from the sale and replace all the debt retired when acquiring the replacement property.
3. Violation of time frames. Solution: Understand the 45-day and 180-day rules; use a QI to manage.
4. Misidentification. Solution: Use identification rules and unambiguous descriptions in writing provided to the QI.
5. Change of entity. Solution: Acquire replacement property in same entity registration format as the relinquished property was titled.
Delaware Statutory Trusts
Legal structure and IRS acceptance
Governed by the Delaware Statutory Trust Act, DSTs are trust entities that allow numerous investors to possess fractional shares in real property through beneficial ownership of the title-holding trust.30 Investors in a DST are not direct owners of the real estate, but instead own an undivided beneficial interest in the assets held by the trust, while the DST holds title to the property for the benefit of its many investors.
In 2004, the IRS recognized DSTs’ beneficial interest as qualified/likekind replacement property for real property relinquished within § 1031 exchanges.31 Via Rev. Rul. 2004-86, the IRS importantly distinguished DSTs from limited partnership interests for the purpose of § 1031 transactions. The IRS further specified that beneficial interests are synonymous with direct ownership interests under § 1031, that debt must be allocated pro rata for exchange purposes, and that active management must be conducted by the DST and not by its beneficial interest holders.32
Consequently, this revenue ruling effectively made it possible for taxpayers to conduct a qualifying § 1031 exchange transaction in a manner that incorporates passive management strategies of the replacement property. In other words, the taxpayer is no longer relegated to being actively involved in the continual management of their replacement property, as was customary practice with most § 1031 exchanges, should the taxpayer instead prefer to take a more passive role while still retaining the tax benefits of owning such directly held real estate interests.
“Seven deadly sins”: IRS DST structural requirements
While Rev. Rul. 2004-86 effectively opened the § 1031 door to DSTs, the IRS tempered its acceptance of using such structured vehicles within the private letter ruling by requiring DSTs be limited in the actions they may take. As such, DSTs may not:
- obtain additional capital.
- acquire additional debt or refinance current debt.
- reinvest any subsequent sale proceeds.
- make capital expenditures; they are limited to making normal repair and maintenance expenses.
- enter into new leases or renegotiate existing leases.33
- invest cash between distribution dates to the beneficial owners in anything other than short-term securities.
DSTs must also distribute all cash (other than necessary reserves) on a current consistent basis.
To deal with these limitations, DSTs tend to contain provisions for springing into a limited liability company taxed as a partnership (commonly known as a “springing LLC”) if action prohibited by the IRS within the DST format is needed. While this action is normally not taxable, it does run the risk of limiting future § 1031 exit options.
Tenants, toilets, and trash: DSTs and passive management
Among seasoned real estate investors, the burdens of active property management are often summarized — somewhat tongue-in-cheek — by “tenants, toilets, and trash.” This trinity of persistent frustrations often cause once-eager real estate investors to begin searching for viable exit ramps as they face the day-to-day oversight of active property operations and management. The operational realities of being a landlord often detract from the financial rewards, particularly as investors age or desire a more hands-off approach.
The first of these challenges, tenants, require continuous attention: screening applicants; collecting rent; supervising the property to prevent or mitigate misuse, neglect, or damage; or engaging in the eviction process.
“Toilets,” a stand-in for the broader category of property maintenance issues, is the ever-constant reminder that physical structures require upkeep. Unfortunately, that sometimes means plumbing issues arising at 3 a.m. requiring immediate attention, which threaten not only the profitability of the investment, but also the ability to preserve the value of the investment itself.
“Trash” refers to the physical deterioration and cleanup that often follows tenant turnover. Whether that’s fumigating a rental house, removing abandoned property, or repairing damages and repainting walls, the task of keeping the property marketable for future tenants can quickly erode both the net income and patience of the real estate investor.
DSTs enable real estate investors to move from active management to passive management. Because the DST is a passive real estate investment vehicle, the purchase, financing, management, and eventual sale of the property is the responsibility of the DST sponsor to perform — not the investor. Thus, the investor can continue to enjoy the benefits of owning real property without the hassle of day-to-day management.
… And the other “T”: taxes
Given these cumulative challenges, many long-term real estate investors eventually desire an exit ramp that might enable them to reallocate the value of their investment into other areas, provided such can be accomplished in a tax-efficient or tax-neutral manner.
 However, they are often quickly disabused of that notion by their lawyers and CPAs, who proclaim that a non-strategic exit from this real estate arena will likely trigger material tax consequences. If the advisor explains the § 1031 exchange process but neglects to include the DST option for consideration, then the investor can be left with the false impression that they are relegated to a lateral investment move, and maybe further additional capital outlay, via exchanging the currently owned property for another physical like-kind property. Thus, the investor risks wrongfully concluding their only effective option is to “trade one problem for another.” Conversely, DSTs can provide the client with an option that may materially change their current investment situation, while doing so in a tax-neutral manner.
Those clients who entirely disregard the § 1031 option run the risk of not only having their transaction be subject to federal and state taxes for capital gains, but also two additional taxes: Depreciation Recapture Tax (DRT)34 and the Net Investment Income Tax (NIIT) of the Affordable Care Act.35 Consequently, it is not uncommon for a client-investor to be forced to cede the majority of their sales proceeds to paying various tax liabilities if a transaction is not properly structured to incorporate the tax benefits of § 1031.
DRT is perhaps the most often overlooked and financially significant component in the sale of real estate. Real estate investors typically depreciate the structure, but not the land, of rental income-producing property over a 27.5-year or 39-year schedule.36 When the real property is sold, the IRS “recaptures” that depreciated amount via a flat 25% tax rate.
A lesser-known but increasingly relevant component of the overall tax burden is the 3.8% NIIT imposed by the Affordable Care Act. This surtax applies to net investment income, including capital gains, for taxpayers whose modified adjusted gross income (MAGI) exceeds certain thresholds — $250,000 for married couples filing jointly and $200,000 for single filers. The 3.8% tax is applied to the lesser of the taxpayer’s net investment income or the amount by which their MAGI exceeds the threshold.37
Suppose a married couple filing jointly has $450,000 in MAGI and $700,000 in capital gains from selling three rental properties. Since their MAGI exceeds $250,000 by $200,000 ($450,000 minus $250,000) and their net investment income from the sale of the houses is $700,000, the 3.8% NIIT is assessed against the lower value ($200,000). This NIIT causes an additional $7,600 in federal tax liability incurred by the couple.
Using a DST via a § 1031 exchange can defer not only federal and state capital gains taxes but also DRT and NIIT. Moreover, the investor can keep deferring this total tax liability into future DSTs, or return to direct ownership, until they pass away. At death, the investor’s beneficiary is still entitled to receive a step-up in the cost basis of the investment, thereby significantly mitigating, if not entirely eliminating, this overall deferred tax liability, while still permitting the client-investor to enjoy the tax benefits of real estate investment during their lifetime.
Additional advantages of using DSTs in § 1031 exchanges
For real estate investors desiring to transition away from active management, better diversify their real estate holdings, or streamline their estate and tax planning, DSTs can offer unique strategic advantages over the options typically used for real property replacement. DSTs offer the following potential advantages:
- Access to institutional-quality real estate. The multi-trillion-dollar U.S. commercial property market may be a challenge to navigate for individual investors. Partnering with a respected DST sponsor with local market knowledge, who has access to institutional-quality properties coupled with expertise in management and financing, can help real estate investors expand their options when looking for replacement property. Using this strategy, for example, an investor could potentially exchange their apartment complex interest into a DST that owns a $70-million distribution center. On their own, the investor would likely never be able to afford or manage such an asset.
- Diversification. Financial advisors typically advocate their clients to obtain exposure to various asset classes to reduce overall portfolio risk. DSTs can aid in accomplishing the diversification and risk management objectives by exchanging one type of real property into several different types of real estate classifications. DSTs usually have flexible minimum investment amounts enabling investors to exchange into multiple offerings. DST investments can offer multiple property portfolios across a variety of property types (commercial, industrial, multi-family, etc.), as well as broad geographic locations. For example, a real estate investor could exchange their eight rental properties, all held in Columbia and classified as residential real property, for a DST that holds real property assets in industrial (Garland, Texas), commercial (Miami, Florida), and residential (Nashville, Tennessee), thereby accessing multiple sectors and different geographic locations.
- Nonrecourse debt.38 When an individual owns a building, they are responsible for repayment of debt if a default occurs. DSTs, however, typically use nonrecourse financing. The sponsor of the program (i.e., trustee) takes on the liability and is responsible for any debt repayment on the property. While there is always risk involved with owning real estate, nonrecourse financing limits the liability for DST investors.39 For investors approaching retirement and considering selling property to simplify their lives, a DST also helps solve the dilemma of trying to secure a mortgage on a replacement property at a time when the investor’s earned income may become reduced due to retirement, which might make qualifying to obtain future financing more of a challenge.
- Simplified tax reporting (grantor letter). Tax lawyers and CPAs typically dread the Schedule K-1 form. Not only do they tend to be issued late in the tax season, they’re also complex and require significant skill and time to process. Most real estate holdings, including securitized real estate, cannot avoid K-1 reporting. However, DSTs can bypass Schedule K-1 and issue a grantor trust letter that exhibits the DSTs’ allocable income and expenses. The grantor trust letter streamlines the tax filing process as compared to the K-1 form.
- Closing efficiency. Investor and DST sponsor transaction costs may be lower because of less lender paperwork. In addition, the DST sponsor arranges financing and manages all due diligence efforts. Often in a § 1031 exchange where a lender is involved, the lender requires a Special Purpose Entity to isolate financial risk on the specific real property. Not only does the Special Purpose Entity creation add more time and start eating away at the 180-Day Rule, but the creation tends to generate more expenses, such as legal fees, for the investor.
- Relief from underperforming real estate. After factoring in the true
 costs of real estate ownership, many investors find they own property that provides little or no net income, but they are still hesitant to sell and be forced to recognize capital gains taxes along with DRT and NIIT. A § 1031 exchange using a DST may provide a solution to increase cash flow while deferring any taxable event by replacing the property not generating sufficient cash flow for a DST designed to do such.
- Estate planning. Some investors prefer being active real estate owners, while their heirs may wish to be passive owners. A DST can be a powerful estate planning tool. DST interests can be divided amongst beneficiaries, leaving each to decide what to do with their own portion, while the basis on the property steps up to fair market value upon the original owner’s death.40 This strategy is effective for many owners of family farms. Family farm owners are often asset-rich and cashpoor; they understand the tax liability in selling the farm, and often, they have children who either do not want to take over the farm or cannot get the financing to purchase the farm from the parent that would enable the parent to retire. The § 1031-to-DST strategy solves the exit and retirement problem, and it can solve the estate distribution problem as well.
- Return to active management. If the investor longs for the days of “tenants, toilets, and trash” and wishes to return to actively managing investment real estate, the investor always retains that option. Once the DST liquidates, they can simply use the standard § 1031 exchange via like-kind property swap and exit out of the passive management scenario without incurring capital gain or triggering NIIT or DRT and instruct the QI to acquire a directly owned real estate interest of their choosing.
- Eminent domain, destroyed property, and § 1033 exchanges. Investment properties that have been subject to eminent domain or destruction (fire, flood, etc.) may be eligible for a § 1033 exchange. A § 1033 exchange applies when a property is lost through casualty, theft, or condemnation, and incurs capital gains from the proceeds received to pay for the loss.41 As in § 1031 exchanges, a DST may be a replacement solution for these types of exchanges, too.42 Similar to a § 1031 exchange, if reinvested proceeds meet the requirements for the exchange, then capital gains may be deferred. However, unlike § 1031, a § 1033 exchange can be utilized by the investor even if the event took place in the past two or three years and if the investor already took receipt of the proceeds.
Disadvantages of using DSTs in § 1031 exchanges
While the advantages of DSTs are compelling, there are several disadvantages that can make the § 1031-to-DST exchange an inappropriate investment. These include, but are not limited to:
Illiquidity. Upon acquisition of a beneficial interest in a DST, an investor generally lacks the ability to sell, assign, or redeem that interest at will. Instead, recovery of principal is typically possible only upon the occurrence of a liquidity event — a sponsor-initiated transaction that converts the underlying real estate asset into cash or a cash-equivalent interest.
Liquidity events most commonly arise through: (1) the sale of the DST-owned real property; (2) a DST-level § 1031 exchange into replacement real estate; or (3) a contribution of the DST property to a real estate investment trust operating partnership pursuant to IRC § 721, commonly referred to as an UPREIT transaction. Less commonly, a liquidity event may occur following the conversion of the DST into a partnership structure — often termed a “springing LLC” — to address operational exigencies, though such conversion may restrict future § 1031 exchange eligibility.
For example, assume an investor completes a § 1031 exchange into a DST that owns a $50 million multi-tenant industrial property. The offering documents project a seven-year holding period. During that time, the investor receives periodic income distributions derived from rental operations but has no contractual right to liquidate their beneficial interest. At the conclusion of year seven, the DST sponsor determines that market conditions are favorable and sells the property. After satisfaction of outstanding debt and transaction expenses, the net proceeds are distributed to the beneficial owners. This sale constitutes the liquidity event. At that juncture, the investor must elect whether to reinvest the proceeds through another § 1031 exchange or recognize the previously deferred capital gains, DRT, and NIIT surtaxes.
 This framework underscores that liquidity in a DST is event-driven, sponsor-controlled, and time-uncertain. Accordingly, lawyers advising clients considering DST investments should emphasize the necessity of aligning the investment horizon, cash flow needs, and risk tolerance with the structural limitations inherent in DST ownership.
- Complete absence of public secondary markets for DST interests. Since DST shares are illiquid, a public secondary market does not exist for investors or others to buy and sell their shares. However, there is a silver lining associated with this aspect: Since there is no public secondary market, the DST shares are marginally correlated to equity markets. Thus, their value tends to remain constant while traditional shares in equities see greater volatility as they are traded. Investors holding securitized real estate, such as a DST, generally must demonstrate that they have a low need for liquidity. Unfortunately, circumstances sometimes arise that change that dynamic, and when they do, investors in DSTs and other illiquid assets will receive unsolicited deeply discounted third-party offers for their interests.
- Long-term time horizons and holding periods. Typically, DSTs tend to exist between five and seven years before the sponsor will consider initiating any type of liquidation process. During that time, if the DST is successful, it will pay its beneficial owners a distribution of the income derived from the underlying property, generally on a monthly basis. So, an investment property holder using DSTs as replacement properties to execute a § 1031 exchange strategy is at the mercy of the DST sponsor as to when they can exit the investment. Conversely, if the investor holds on to their physical property, the investor retains the freedom to sell it at any time they deem beneficial.
- Lack of investor control. As stated above, the investor loses decision control when entering the DST. The decision of when to sell the DST is determined by the sponsor. Unlike traditional stocks, there are no voting rights associated with an investor’s beneficial ownership interest. When a DST is sold, the investor can rollover sales proceeds into another DST (e.g., keep kicking the proverbial tax can down the road until death when beneficiaries can receive a step-up in cost basis), exchange the sales proceeds into a new directly held property, or cash out and pay taxes.
- Fees and costs. DST investments tend to be more expensive than other traditional investments. They also incur relatively high management fees to pay for the professional team operating them, which eat into the investor’s yield, unless significant tax savings from deferral can be obtained.
- Inflexibility of structure. As previously mentioned, DSTs are prohibited from refinancing, making capital improvements, or amending/altering the lease terms. Properties held in a DST could fall into dereliction if not properly managed or if minor repairs would be futile. Thus, it is imperative to evaluate the operational results and reputation of each DST sponsor to mitigate this risk.
- General real estate risks. Just as in holding any physical real property, DST beneficial owners assume the same general and market-related risks of changes in cap rates, variations in occupancy, loss of tenants, loss of principal, rising interest rates, limited liquidity, and inflation.
- Accredited investor status. Like most private placement and securitized real estate investments of an illiquid nature, DSTs can only accept accredited investors as defined by the Securities and Exchange Commission.43 To meet the definition, an investor must have a net worth, excluding primary residence and personal property, that is $1 million or more. Trusts not formed for the specific purpose of acquiring the securities being offered must have total assets greater than $5 million, but this high threshold can be waived for grantor trusts where each trustee meets the individual criteria for being an accredited investor. If the investor fails that net worth test, then the investor can qualify by providing the past two years of their tax returns showing at least $200,000 of individual income or $300,000 in joint spousal income. Many investors who possess lower-valued real property, such as rental houses for college students, might find the accredited investor status requirement barring their use of a DST.
- Tax law changes. While the § 1031 exchange has existed since 1921,44 it tends to be a candidate for elimination (or is often used as a negotiation tool) during tax policy discussions on Capitol Hill. Even though it is unlikely to be eliminated, it is not immune from substantial changes, such as when the sale of personal property became ineligible for § 1031 exchange benefits in 2017.45 The most recent major legislation, the One Big Beautiful Bill Act,46 resulted in no changes to § 1031, DSTs, or the likekind definition. Further, OBBBA placed no new limitations, caps, or phase-outs on § 1031 transactions.47 Again, while the sun still shines on § 1031 exchanges, new legislation can always bring about a sunset.
One last § 1031 wrinkle: Section 721 UPREIT Exchange
The intersection of DST investments, § 1031 like-kind exchanges, and so-called “UPREIT” transactions presents one of the more sophisticated and consequential tax planning crossroads in modern real estate practice.
The ultimate moment of decision arrives when DST sponsors offer investors the opportunity to convert their fractional real estate beneficial interests into Operating Partnership units (OP units) through a § 721 contribution to a Real Estate Investment Trust’s (REIT) umbrella partnership.48 The choice to accept such units carries significant implications for future tax deferral strategies, including the ability — or inability — to execute subsequent § 1031 exchanges.
What lawyers, CPAs, and other advisors need to know about the § 721 UPREIT process is that, while there is a proper time and place for it, when their client enters the UPREIT, they are now in a § 1031 dead end. That client can no longer conduct a subsequent § 1031 exchange using those particular proceeds. This distinction creates what tax practitioners often describe as a “one-way election.”
Further, when an investor selects the UPREIT option, the OP units become commingled with other REIT properties in the sponsor’s portfolio. While that can positively improve the investor’s diversification, the investor is now forced to invest in other properties they did not select, while also having no ability to decide whether future properties being added to the REIT portfolio are desirable for their situation.
In addition, when the investor converts their DST beneficial ownership interests to OP units, that conversion is not a taxable event. However, when the REIT sells the OP units at its liquidation event, or when the investor decides to liquidate a portion of their REIT interest, an unavoidable taxable event occurs. The investor must now recognize tax liability on the deferred capital gains, DRT, and NIIT.
One of the advantages often expressed in advising a client to accept the § 721 UPREIT option is the limited liquidity feature of the REIT in comparison to the essentially non-existent liquidity aspect inherent with DSTs. Like DSTs, REITs generally are not publicly traded, so they do not offer a secondary market sale option. Instead, the REIT sponsor tends to offer a Share Repurchase Program where the sponsor offers shareholders a stated share price for a limited number of shares to be redeemed. However, this particular liquidity provision is almost always limited and never guaranteed — and it is not uncommon for the REIT sponsor to suspend or terminate the program.
Lawyers, CPAs, and other advisors should remain cautious that converting DST interests into OP units effectively closes the door to conducting future § 1031 exchanges for that real estate asset. That does not mean such transactions should be dismissed out of hand. For some investors, the opportunity to more broadly diversify their holdings, gain some measure of liquidity, and shift the management of their real estate assets to professional institutions can outweigh the disadvantages.
Conclusion
Using DSTs as replacement properties to execute a § 1031 exchange strategy is not appropriate for all real estate investment holders. However, when properly structured, the DST option provides significant tax and utility advantages for investors and retiring business owners to consider. It can enable such people to exit the active management duties and accompanying liabilities intrinsically attached to holding physical real property, while also providing the benefit of a consistent income stream that is marginally correlated to the performance of equity markets.
Although gaining in popularity, this viable strategy continues to be significantly underutilized today due to lack of option awareness by lawyers, CPAs, and other financial professionals. Thus, acquiring a competent understanding of the strategy’s availability, along with its advantages and drawbacks, will empower lawyers to better advance their clients’ interests in securing appropriate tax deferrals, improving asset diversification, and accomplishing valuable estate planning objectives.
This article is neither an offer to sell nor a solicitation of an offer to buy any security which can only be made by prospectus. Investing in real estate and § 1031 exchange replacement properties may not be in the best interest of all investors and may involve significant risks. Investors should understand all fees associated with a particular investment and how those fees could affect overall performance. Neither Diversify, DFPG or its representatives provide tax or legal advice, as such advice can only be provided by a qualified tax or legal professional, who all investors should consult prior to making any investment decision. Wealth management services through various unaffiliated companies including advisory services offered by Diversify Wealth Management, LLC (“Diversify”) and Integrated Advisory Services, LLC (“IAN”) SEC registered investment advisers. Additional investment services and securities through DFPG Investments, LLC., a broker/dealer, member FINRA/SIPC, and an affiliate of Diversify. IAN is not affiliated with Diversify or DFPG.
Endnotes
1 J. Max Nowakowski, The Basics of a 1031 Like-kind Exchange, 95 OKLA. B.J. 42 (June 2024).
2 Rev. Rul. 2004-86, 2004-2 C.B. 191.
3 I.R.C. §1031(a)(1) (2025).
4 Id.
5 Id.
6 Treas. Reg. §1.1031(a)-1(b) (as amended in 1991).
7 I.R.C. §1031(h) (2025).
8 I.R.C. §1031(a)(2) (2025).
9 Sparks v. United States, 138 F. Supp. 603 (W.D. Ark. 1956).
10 I.R.C. §1031(a)(3)(A) (2025).
11 Treas. Reg. §1.1031(k)-1(b)(2)(i) (as amended in 1991).
12 Treas. Reg. §1.1031(k)-1(c)(4)(i)(A) (as amended in 1991).
13 Treas. Reg. §1.1031(k)-1(c)(4)(i)(B) (as amended in 1991).
14 Treas. Reg. §1.1031(k)-1(c)(4)(iii) (as amended in 1991).
15 I.R.C. §1031(a)(3)(B)(ii) (2018).
16 Treas. Reg. §1.1031(k)-1(b)(2)(ii) (as amended in 1991).
17 I.R.C. §1031(h) (2025).
18 Treas. Reg. §1.1031(b)-1(a) (as amended in 1991); Alderson v. Commissioner, 317 F.2d 790 (9th Cir. 1963).
19 Treas. Reg. §1.1031(b)-1(c) (as amended in 1991).
20 Ocmulgee Fields, Inc. v. Commissioner, 132 T.C. 105 (2009).
21 Priv. Ltr. Rul. 200251008 (Sept. 11, 2002).
22 I.R.C. §1031(a)(1) (2025).
23 Treas. Reg. §1.1031(k)-1(g)(7) (as amended in 1991).
24 I.R.C. §1001(a) (2025).
25 Treas. Reg. §1.1031(k)-1(g)(4)(i) (as amended in 1991).
26 Maloney v. Commissioner, T.C. Memo. 2000-34; Treas. Reg. §1.1031(a)-1(b) (as amended in 1991).
27 Rev. Rul. 75-292, 1975-2 C.B. 333.
28 I.R.C. §1031(a)(1) (2025); Treas. Reg. § 1.1031(a)-1(a) (as amended in 1991).
29 I.R.C. §1031(a)(1) (2025); I.R.C. §§ 871–882 (2025); I.R.C. §897 (2025); Priv. Ltr. Rul. 9853024 (Oct. 1, 1998).
30 Del. Code Ann. tit. 12, § 3801 et seq. (2023).
31 Rev. Rul. 2004-86, 2004-2 C.B. 191. “Holdings: (1) The Delaware Statutory Trust is an investment trust, under §301.7701-4(c), that will be classified as a trust for federal tax purposes. (2) A taxpayer may exchange real property for an interest in the
Delaware Statutory Trust without recognition of gain or loss under §1031, if the other requirements of §1031 are satisfied.”
32 Id. “… interests in the trust may be qualifying property in a tax-deferred, like-kind exchange if the other requirements for such treatment are satisfied.”
33 Id. Except in the event of an original tenant bankruptcy or insolvency.
34 26 U.S.C. §1250(a); IRS Pub. 544, Sales and Other Dispositions of Assets (2023).
35 26 U.S.C. §1411 (2025).
36 IRS Publication 527, Residential Rental Property § 2 (2024); IRS Publication 946, How to Depreciate Property § 4 “Recovery Periods Under GDS” (2024).
37 Net Investment Income Tax, Topic No. 559, Internal Revenue Service; Instructions for Form 8960, 2024; 26 U.S.C. § 1411 (Net Investment Income Tax).
38 Priv. Ltr. Rul. 200521002 (May 27, 2005).
39 Delaware Statutory Trust Act, 12 Del. C. § 3801 et seq.; Rev. Rul. 2004-86; Instructions for Form 6198 (2024), At-Risk Rules (Treas. Reg. § 1.465-27); 26 C.F.R. § 1.465-27 (Qualified Nonrecourse Financing).
40 I.R.C. §1014(a) (2025).
41 I.R.C. §1033 (2025).
42 Private Letter Ruling (PLR) 200644019 (Nov. 3, 2006). Although not precedent, this PLR allowed a taxpayer to use DST interests as replacement property in a §1033 exchange after a condemnation.
43 17 C.F.R. §230.501(a) (2025).
44 Revenue Act of 1921, ch. 136, §202(c), 42 Stat. 227, 230 (1921).
45 Tax Cuts and Jobs Act, Pub. L. No. 115-97, §13303, 131 Stat. 2054, 2124 (2017).
46 Public Law 119-21, An Act to provide for reconciliation pursuant to title II of H. Con. Res. 14, 139 Stat. 72 (July 4, 2025).
47 Evan Liddiard, “Big Beautiful” Tax Bill Now Law: In-Depth Analysis, Nat’l Ass’n of REALTORS, (Jul. 14, 2025), Big Beautiful Tax Bill Now Law: In-Depth Analysis, NAR, nar.realtor/washington-report/big-beautiful-tax-bill-now-law-in-depth-analysis.
48 26 U.S.C. § 721(a): “No gain or loss shall be recognized to a partnership or to any of its partners in the case of a contribution of property to the partnership in exchange for an interest in the partnership.”; Treas. Reg. § 1.721-1(a): confirms that the contributor receives a partnership interest in exchange for the contributed property.